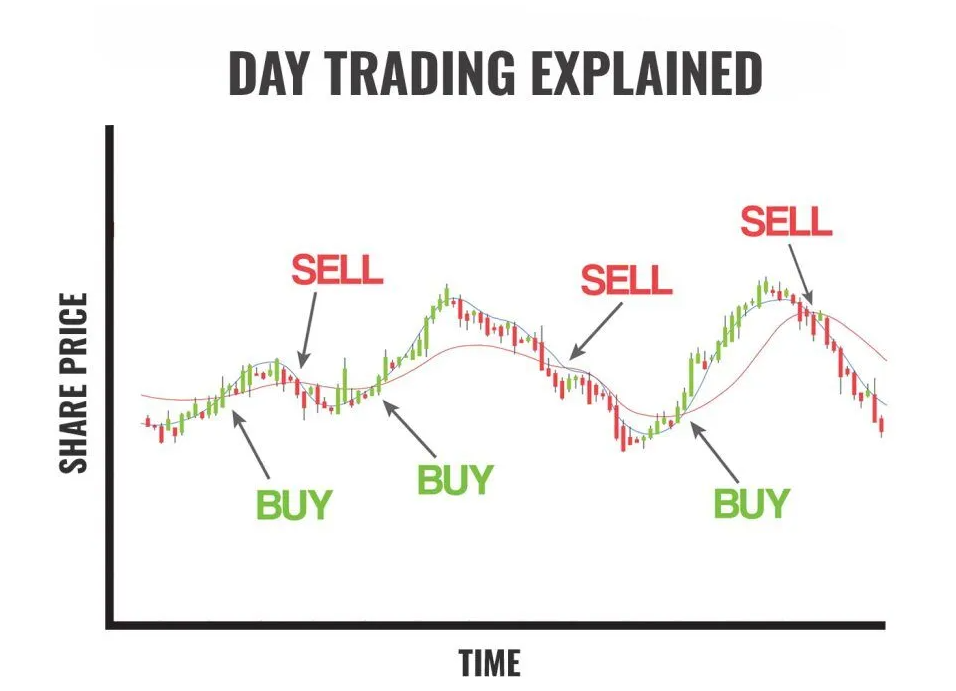
If you are interested in stock markets, you may eventually ask, how old do you have to be to day trade? Day trading can seem appealing because it involves buying and selling financial assets over short periods, sometimes within the same trading day. However, age is an important consideration because opening and controlling a brokerage account generally requires you to meet certain legal and brokerage requirements. For people in the United States, the practical minimum age for independently opening a standard brokerage account is generally 18, although the exact requirements can depend on the brokerage, account type, state law, and financial product involved. Minors may have access to certain custodial or specialized accounts, but those accounts do not necessarily provide the same control as an adult brokerage account. Age is also only one part of the picture. Day traders need to understand brokerage requirements, trading rules, account minimums, taxes, risk, and the differences between cash and margin accounts. This guide explains how old you have to be to day trade, what minors can do, how custodial accounts work, and what new traders should understand before putting money into the market. How Old Do You Have to Be to Day Trade? For someone in the United States who wants to independently open a regular brokerage account, 18 is generally the important age threshold. At that age, an individual can generally enter into financial agreements and open an investment account in their own name, subject to the brokerage’s requirements. However, being 18 does not automatically mean that you can day trade without restrictions. Your brokerage may have additional requirements, and trading certain products may involve additional eligibility standards. Day trading also has specific regulatory requirements. For example, FINRA’s rules impose special requirements on customers classified as pattern day traders, including a $25,000 minimum equity requirement. Therefore, the answer to “how old do you have to be to day trade” is only the first part of understanding whether you can actually begin trading. Can You Day Trade If You Are Under 18? Minors generally cannot simply open a standard brokerage account and independently trade securities in the same way as an adult. However, there are account structures designed to allow minors to invest with the involvement of a parent, guardian, or other authorized adult. A custodial account is one common example. In a custodial arrangement, an adult custodian manages the account for the benefit of the minor until the applicable transfer age under state law. The exact investment options available through a custodial account depend on the brokerage and account structure. A custodial account should not automatically be assumed to provide unrestricted day-trading access. If you are under 18 and interested in learning about trading, you can also spend time developing market knowledge before using real money. Understanding stocks, orders, risk management, financial statements, and market volatility can be valuable regardless of your age. What Is a Custodial Brokerage Account? A custodial brokerage account allows an adult to manage investments on behalf of a minor. The minor is the beneficiary, but the custodian generally controls the account while the child is under the applicable age. This structure can allow young people to participate indirectly in investing before they reach adulthood. However, it is different from having complete control over a personal brokerage account. Parents or guardians considering a custodial account should review the brokerage’s rules and understand which securities and transactions are permitted. If the goal is specifically day trading, it is especially important to ask the brokerage whether the account type supports the intended activity. A regular custodial investment account should not automatically be treated as a day-trading account. Can a 16-Year-Old Day Trade? A 16-year-old generally cannot independently open a standard brokerage account and day trade stocks under their own authority in the same way an adult can. A parent or guardian may be able to establish an appropriate account structure for a minor, depending on the brokerage and applicable law. However, that does not necessarily mean the minor can independently execute unlimited day trades. For teenagers interested in financial markets, a more practical approach can be to focus on education, simulated trading, and learning how markets operate. Paper-trading platforms can allow beginners to practice strategies without risking actual capital. The rules surrounding minor accounts can vary, so families should verify the specific requirements with the brokerage before opening an account. Can a 17-Year-Old Day Trade? At 17, you are still legally a minor in most U.S. contexts, so you generally cannot independently operate a standard brokerage account as an adult account holder. Some investment account structures allow a parent or guardian to manage investments for a minor. However, the ability to buy and sell frequently depends on the account’s terms and the brokerage’s policies. If you are approaching 18, using the time before adulthood to learn about markets can be useful. By the time you are eligible for your own brokerage account, you can have a better understanding of market orders, volatility, risk, and trading costs. Can You Day Trade at 18? Once you reach 18, you can generally become eligible to open a brokerage account in your own name, assuming you satisfy the brokerage’s other requirements. However, being 18 does not eliminate the financial risks of day trading. A new adult trader still needs to understand the difference between cash and margin accounts, the risks of leverage, commissions and fees, taxes, and applicable trading rules. FINRA specifically warns that day trading can be extremely risky and states that traders should be prepared to lose the funds used for day trading. Therefore, reaching the minimum age should be viewed as an eligibility milestone rather than a signal that someone is financially prepared to trade. What Is the Pattern Day Trader Rule? The pattern day trader concept is particularly important for people researching day trading in the United States. Under FINRA’s current rules, a customer who executes four or more day trades within five business days can be classified as
The Complete Guide to Modern Banking and Smart Money Management
Banking has become an essential part of everyday financial life. People use bank accounts to receive salaries, pay bills, transfer money, save for future goals, and manage regular expenses. At the same time, modern banking has changed significantly because of digital technology. Customers can now complete many transactions through mobile apps and online banking without visiting a physical branch. Understanding how modern banking works can help you make better financial decisions. Whether you are opening your first account, improving your savings strategy, or learning how to manage everyday expenses, having a clear understanding of banking fundamentals can make money management easier. Understanding Modern Banking Traditional banking required customers to visit branches for many common services. Today, banks offer a combination of physical and digital services. Online banking allows customers to check balances, transfer funds, pay bills, download statements, and manage various account settings from a computer or smartphone. Mobile banking has made financial management even more convenient. Banking applications often provide real-time account information, transaction notifications, digital payments, and security features. Despite these technological changes, the basic purpose of banking remains the same. Banks provide financial accounts and services that help individuals and businesses manage, save, borrow, and move money. Choosing the Right Bank Account Selecting an appropriate bank account is an important part of financial planning. Different accounts serve different purposes, so it is useful to understand what each one offers. A checking or current account is generally designed for everyday transactions. It may be used for receiving income, paying bills, making purchases, and transferring money. Savings accounts are intended primarily for setting aside money. Depending on the account and financial institution, customers may earn interest on their savings. When comparing accounts, look beyond convenience. Consider fees, minimum balance requirements, interest rates, transaction limits, accessibility, digital features, and customer support. Create a Practical Monthly Budget Smart money management begins with knowing where your money goes. A monthly budget provides a simple way to organize income and expenses. Start by calculating your regular income. Then list essential expenses such as housing, utilities, groceries, transportation, insurance, and loan payments. After that, consider discretionary spending such as entertainment, dining, shopping, and subscriptions. Once everything is listed, compare your total expenses with your income. If spending consistently exceeds income, identify areas where adjustments can be made. A budget does not have to be complicated. Even a simple spreadsheet or budgeting application can provide a clearer picture of your financial habits. Build an Emergency Fund Unexpected expenses can happen at any time. Car repairs, home maintenance, medical costs, or temporary income disruptions can put pressure on a household budget. An emergency fund provides a financial cushion for situations that are difficult to predict. The appropriate amount depends on individual circumstances, income stability, expenses, and financial responsibilities. Keep emergency savings in an account that is relatively accessible while remaining separate from money used for everyday spending. Building the fund gradually can make the process more manageable. Even small, regular contributions can help establish a useful financial safety net over time. Use Credit Responsibly Credit cards and other forms of credit can be useful financial tools when managed responsibly. They can provide convenience, help with certain purchases, and potentially offer rewards or other benefits. However, borrowing more than you can comfortably repay can lead to growing interest charges and financial stress. Before using credit, understand the interest rate, fees, repayment terms, and consequences of missing payments. Whenever possible, pay attention to your statement and keep track of outstanding balances. Credit should support your financial goals rather than become a substitute for income. Protect Your Online Banking Digital banking provides convenience, but security should always be a priority. Use strong, unique passwords for banking accounts and avoid sharing login credentials with others. Enable multi-factor authentication when your bank offers it. This can provide an additional layer of protection beyond a password. Be cautious with unexpected emails, text messages, or phone calls requesting banking information. Fraudulent messages may attempt to create urgency and persuade you to reveal passwords, verification codes, or account details. Always access your bank through its official website or trusted mobile application rather than clicking suspicious links. Monitor Your Transactions Regularly checking your bank statements and transaction history can help you identify mistakes, unexpected charges, and potentially unauthorized activity. Make it a habit to review your account periodically. Banking notifications can also be useful because they may alert you when payments, transfers, or withdrawals occur. If you notice a transaction that you do not recognize, contact your financial institution promptly and follow its procedures for reporting the issue. Monitoring your accounts also helps you understand your spending habits. You may discover recurring expenses that you no longer need or areas where spending is higher than expected. Automate Your Savings Saving money consistently can be difficult when you rely entirely on willpower. Automated transfers can make saving more convenient. For example, you can arrange for a specific amount to move from your primary account into a savings account on a regular schedule. This approach makes saving part of your financial routine. You can create separate savings goals for different purposes, such as travel, education, a vehicle, home improvements, or long-term financial needs. The important factor is consistency. A manageable amount saved regularly can become significant over time. Understand Bank Fees Banking fees can quietly reduce your available money if you do not monitor them. Depending on the account and institution, fees may be associated with overdrafts, certain transactions, account maintenance, ATM usage, or other services. Review the fee schedule associated with your accounts. If you notice charges that could be avoided, ask your bank about available account options or alternative services. Comparing banks can also help you identify accounts that better match your financial habits. Plan for Long-Term Financial Goals Smart money management involves more than paying current bills. It also means thinking about future financial needs. Consider what you want to accomplish over the next several years. Your goals might include purchasing a home,
Fintech Solutions That Enhance Convenience, Security, and Efficiency
Introduction Fintech has transformed the financial industry by introducing innovative solutions that make financial services more accessible, convenient, and secure. By combining technology with finance, fintech companies have reshaped how individuals and businesses manage money, conduct transactions, and access credit. From mobile banking to digital wallets and automated investment tools, fintech solutions provide efficiency and flexibility that traditional systems often cannot match. Streamlining Payments and Transactions One of the most noticeable benefits of fintech is the simplification of payments and transactions. Digital wallets, mobile banking apps, and contactless payment systems allow users to send and receive money instantly without visiting a physical bank. These solutions reduce the time and effort required for everyday financial activities, providing seamless experiences for personal and business transactions. Enhancing Security Fintech solutions prioritize security through advanced encryption, biometric authentication, and real time fraud detection. These measures protect sensitive financial data and ensure safe transactions. By offering reliable security features, fintech builds trust and allows users to manage their finances confidently. Secure platforms also reduce the risk of identity theft, unauthorized access, and financial fraud, providing peace of mind for all users. Financial Inclusion Fintech promotes financial inclusion by providing access to banking and credit services for underbanked and unbanked populations. Mobile banking, peer to peer lending, and microfinance platforms reach communities that traditional banking services may not serve. By reducing barriers and offering flexible financial solutions, fintech enables more people to participate in the economy and improve their financial wellbeing. Investment and Wealth Management Fintech platforms have revolutionized investment and wealth management by making these services more accessible and affordable. Robo advisors, online trading apps, and automated investment tools help individuals create personalized portfolios, monitor performance, and make informed decisions. These solutions allow users to invest with lower fees and minimal expertise, democratizing wealth management and encouraging financial growth. Efficiency for Businesses Businesses benefit from fintech solutions that streamline accounting, payroll, invoicing, and expense management. Cloud based platforms and automated tools reduce administrative tasks and improve accuracy, allowing companies to focus on growth and strategy. Fintech also enables faster cross border transactions, better cash flow management, and real time financial insights, contributing to operational efficiency. Innovation and Technology Fintech thrives on innovation, continuously introducing new tools and solutions. Blockchain technology, artificial intelligence, and machine learning improve transparency, decision making, and predictive analytics. Fintech companies experiment with creative approaches to lending, payments, insurance, and financial education. The integration of emerging technologies ensures that financial services evolve to meet changing demands. Personalized User Experiences Fintech solutions provide personalized experiences by analyzing user behavior and offering tailored recommendations. Budgeting apps suggest spending adjustments, investment platforms recommend diversified portfolios, and banking tools alert users to opportunities or risks. Personalization enhances convenience, encourages better financial habits, and improves decision making for individuals and businesses alike. Supporting Economic Growth Fintech contributes to economic growth by expanding access to capital, facilitating transactions, and promoting innovation. Small businesses gain access to loans and payment solutions that enable expansion, while consumers can manage finances more efficiently. By fostering financial participation and efficiency, fintech strengthens both local and global economies. Planning and Financial Literacy Many fintech platforms also promote financial literacy by providing tools, educational resources, and actionable insights. Users can track spending, set goals, and understand financial trends. These resources empower individuals and businesses to make informed decisions and achieve long term financial stability. Education combined with innovative tools maximizes the value of fintech solutions. Conclusion Fintech solutions enhance convenience, security, and efficiency across personal and business financial activities. By streamlining transactions, improving access to financial services, promoting security, and supporting investment and growth, fintech transforms the way money is managed. Innovation and technology continue to expand the capabilities of fintech, offering personalized experiences, operational efficiency, and financial literacy. Embracing fintech empowers individuals and businesses to navigate finances effectively, achieve goals, and participate fully in the modern economy.